Most buyers begin their home search with one question: “How much will the monthly payment be?”
That is an important number—but it is rarely the complete number.
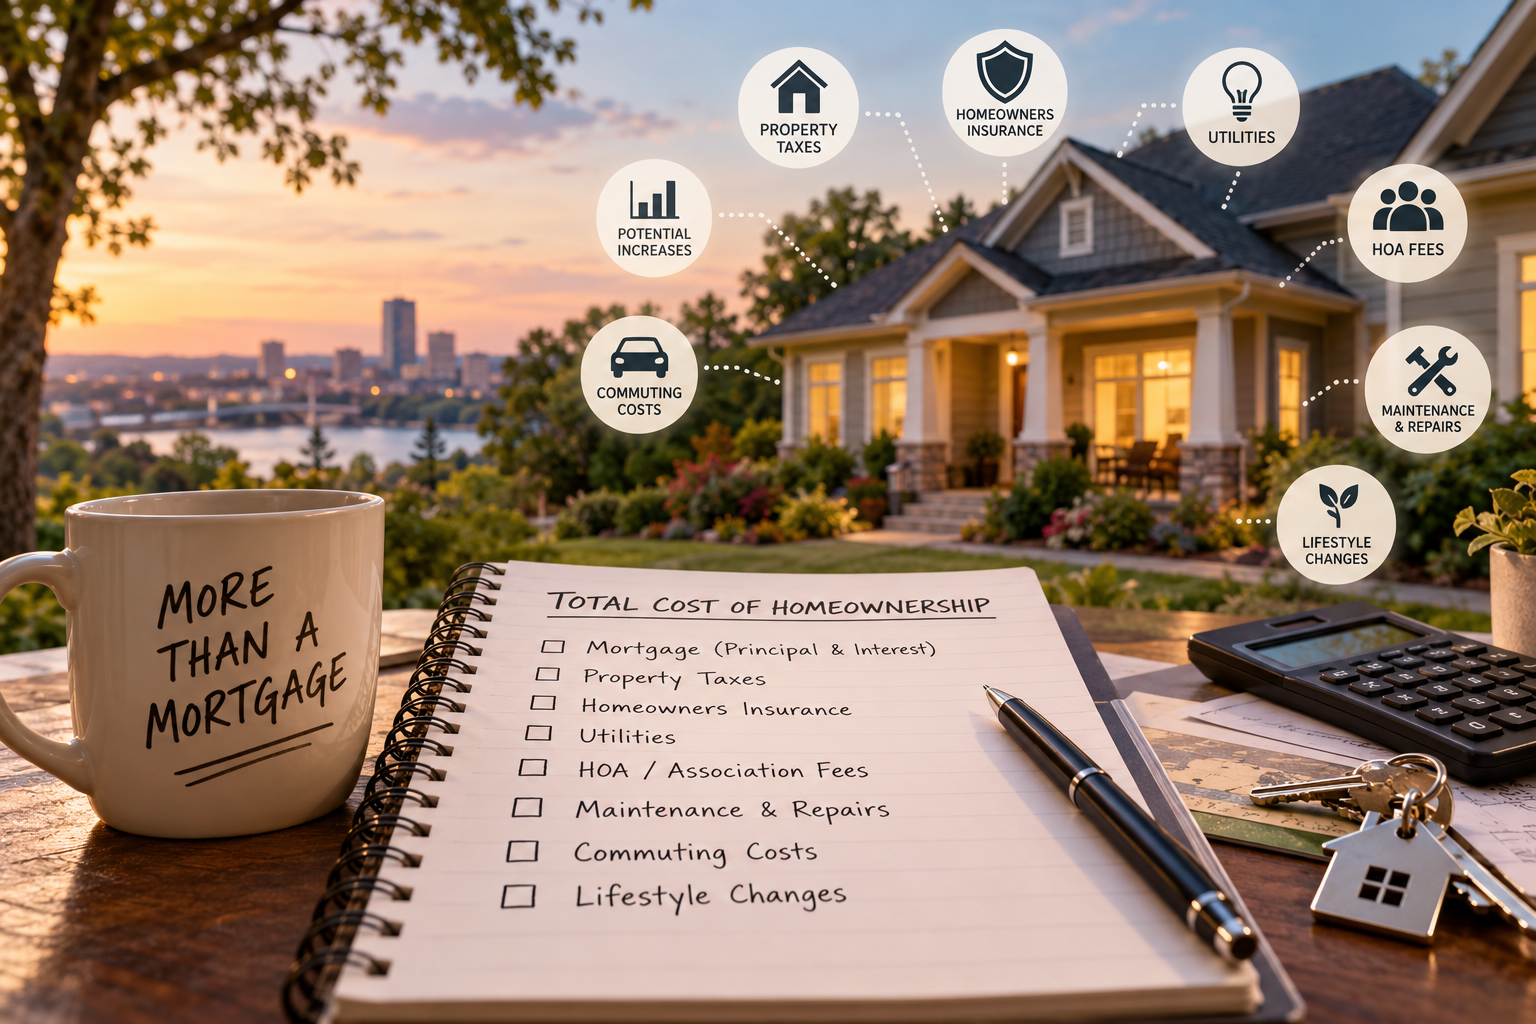
A mortgage estimate may include principal, interest, estimated property taxes, and homeowners insurance. It may not account for rising taxes, changing insurance premiums, utility costs, association increases, maintenance, commuting expenses, or the lifestyle changes that come with a particular neighborhood.
A home that appears comfortable on paper can become financially stressful when another $400 to $800 in recurring expenses begins showing up each month.
The following scenarios are composites based on situations buyers commonly encounter. They illustrate why I encourage clients to consider the cost of living in a home—not simply the cost of purchasing it.
Property Taxes Can Change After Closing
Buyers often assume the seller’s current property-tax bill will remain the same after the sale. That may not be an accurate long-term estimate.
Arkansas property taxes are based on the county assessor’s valuation and the millage rates that apply to the property’s location. Those rates can vary depending on the city, school district, and other taxing authorities.
The seller’s bill may also reflect a homestead credit or another form of tax relief that does not automatically apply to the buyer. Arkansas homeowners who occupy a property as their primary residence may qualify for a homestead property-tax credit, but the new owner must make sure the property is properly registered. Veterans and those over the age of 65 can freeze tax increase and Depending upon how long ago they did it, could dramatically change the future taxes from what they are before the sale.
Because Arkansas taxes are collected after the year in which they are assessed, the impact of a change may not become obvious immediately. A lender’s initial escrow estimate can therefore differ from a later tax bill.
A Common Buyer Scenario
A buyer purchases a Little Rock home with a projected total payment of $1,850 per month. The estimate is based partly on the property’s existing tax information. After the tax and escrow amounts are updated, the monthly payment increases by $115.
That may not sound dramatic, but it adds $1,380 to the household’s annual expenses.
Before making an offer, buyers should review the current tax bill, applicable homestead status, assessment history, and local millage rate. The county assessor and lender can help provide more accurate estimates.
The Escrow Shortage Surprise
Even buyers with fixed-rate mortgages can see their total monthly payments change.
The interest rate and principal-and-interest payment may remain fixed, but taxes and insurance generally do not. If either expense increases and the escrow account does not contain enough money to cover the new bill, the lender may adjust the monthly payment.
The buyer may also have an escrow shortage to repay. That can make the increase feel larger because the new payment may include both the higher projected expense and repayment of the previous year’s shortage.
This is why “fixed-rate mortgage” should not be interpreted as “the exact same total payment forever.”
Older Homes Can Produce Higher Utility Bills
Little Rock has many beautiful older homes, particularly in Hillcrest, the Heights, Midtown, Capitol View, Stifft Station, and surrounding central neighborhoods.
These properties may offer hardwood floors, mature trees, architectural detail, and established surroundings. They may also have older windows, limited insulation, aging ductwork, or heating and cooling systems that work harder during Arkansas summers.
Two homes with similar square footage can have very different utility costs depending on:
- Ceiling height and floor plan
- Window age and condition
- Insulation levels
- HVAC age and efficiency
- Shade and sun exposure
- Gas versus electric systems
- Ductwork condition
- Pool, irrigation, or additional refrigeration equipment
Entergy Arkansas provides bill-analysis and energy-efficiency resources, but the most useful information during a home purchase may be the property’s recent utility history.
A Common Buyer Scenario
A buyer moves from a newer 1,400-square-foot rental into a charming 2,100-square-foot Midtown home. The mortgage payment fits the budget, but the buyer assumes utilities will increase by only $50 or $75 per month.
During the first full summer, the electric bill is approximately $200 higher than expected. The home remains affordable, but the buyer has less room for repairs, travel, and savings.
Before closing, request recent utility averages when available. Remember that another household’s usage will not precisely predict yours, but it can expose a major difference before it becomes a surprise.
Homeowners Insurance Is Property-Specific
Online mortgage calculators often use a broad insurance estimate. Actual premiums can differ substantially between properties with similar prices.
Insurance companies may consider the home’s:
- Roof age and material
- Construction type
- Electrical and plumbing systems
- Claims history
- Distance from emergency services
- Replacement cost
- Deductible
- Flood, wind, or other risk exposure
A lower-priced older home is not guaranteed to cost less to insure than a newer, more expensive property. Roof condition alone can materially affect the premium or the availability of coverage.
Standard homeowners insurance also generally does not cover flood damage. The Arkansas Insurance Department advises consumers to discuss separate flood coverage with an insurance professional.
A Common Buyer Scenario
A buyer compares two homes priced within $10,000 of each other. The first is newer with a recently replaced roof. The second has more character but an older roof and systems.
The estimated mortgage payments appear nearly identical. After receiving actual insurance quotes, the older home costs $140 more per month to insure and carries a higher deductible.
Always request a property-specific insurance quote during the inspection period. Do not rely solely on a general estimate from a mortgage calculator.
Condo and Association Fees Can Increase
A monthly condo or homeowners association fee should be treated as part of the housing payment—not as a separate optional expense.
In a condominium, the fee may cover exterior maintenance, common-area insurance, landscaping, elevators, gates, amenities, or building reserves. However, the amount can change as insurance, labor, utilities, and repair costs increase.
A poorly funded association may also need a special assessment to pay for major expenses. Buyers should review the association’s financial statements, budget, reserve information, meeting minutes, insurance coverage, and any pending assessments. A healthier reserve fund can reduce—but not eliminate—the risk of a future special assessment.
This can be particularly important when evaluating downtown or River Market condominiums, where elevators, structured parking, roofs, common areas, and building systems can create expenses that a detached-home buyer may not expect.
A Common Buyer Scenario
A buyer qualifies comfortably for a downtown condo with a $275 monthly association fee. One year later, the fee increases to $350, and owners are notified of a temporary assessment for building repairs.
The buyer is now paying significantly more each month without receiving additional living space. The purchase may still be worthwhile, but the original budget should have included room for the association’s costs to change.
Commuting Costs Can Offset a Lower Purchase Price
Moving farther from work can provide more house for the money. It can also add fuel, maintenance, depreciation, tolls, childcare complications, and hours of driving.
A buyer choosing between Little Rock, Bryant, Benton, Maumelle, or another surrounding community should calculate the cost of the full commute—not just the distance shown on a map.
Consider:
- Additional weekly mileage
- Fuel consumption
- More frequent oil changes and tires
- Parking expenses
- Time spent in traffic
- Extra childcare time
- The cost of a second vehicle
- Increased restaurant or convenience-store spending
A suburban home that saves $200 per month on the mortgage may not actually reduce household expenses if the move adds $250 in transportation costs.
Drive the likely route during your normal commuting hours before making an offer. A 20-minute Sunday-afternoon drive may be very different during weekday traffic.
Maintenance Is Not a Predictable Monthly Bill—But It Is Still Monthly
Home maintenance rarely arrives as a convenient $150 charge every month. It arrives as a $450 plumbing repair, a $1,200 appliance replacement, or a several-thousand-dollar HVAC expense.
That unpredictability is why buyers should build maintenance into their monthly budget.
In Central Arkansas, seasonal expenses may include:
- Spring landscaping and drainage work
- HVAC servicing before summer
- Higher irrigation or water usage
- Pest and termite protection
- Gutter and roof cleaning
- Leaf removal in mature neighborhoods
- Freeze protection and winter plumbing repairs
- Storm cleanup and tree maintenance
- Pool opening, closing, and equipment service
A newer West Little Rock home may require less immediate system work but could include association dues, irrigation, extensive landscaping, or a larger area to maintain. An older Hillcrest home may have a smaller lot but require more attention to windows, drainage, electrical systems, or exterior woodwork.
The right amount to reserve depends on the property’s age, condition, construction, and major systems. The important step is establishing a monthly home-maintenance fund before something breaks.
Different Neighborhoods Can Change Your Lifestyle Spending
Where you live can influence how you spend money.
A walkable home near Kavanaugh Boulevard, SoMa, or the River Market may reduce certain driving expenses. At the same time, having restaurants, coffee shops, boutiques, and entertainment nearby may increase discretionary spending.
A larger home in Chenal or another West Little Rock neighborhood may encourage more entertaining, landscaping, decorating, or club-related spending. A property near the Arkansas River Trail might lead to new bikes or outdoor equipment. A longer suburban commute may increase takeout spending because there is less time to prepare meals at home.
These are not reasons to avoid a neighborhood. They are reminders that a home purchase often changes more than the mortgage.
A Common Buyer Scenario
A couple purchases near a popular dining and shopping district because they love the ability to walk to restaurants. Their transportation spending decreases slightly, but their restaurant and entertainment budget grows by nearly $300 per month.
They enjoy the lifestyle and do not regret the purchase. However, the neighborhood costs more than their original housing worksheet suggested.
Calculate the “Real-Life Payment”
Before deciding that a home is affordable, I recommend creating a real-life monthly estimate:
Principal and interest
- Property taxes
- Homeowners and flood insurance, if applicable
- Mortgage insurance, if applicable
- HOA or condo fees
- Average utilities
- Maintenance reserve
- Lawn, pool, pest, or other property services
- Additional commuting costs
- Likely lifestyle changes
= Your real monthly housing cost
The goal is not to make homeownership feel intimidating. It is to prevent a buyer from using every available dollar for the mortgage and leaving no margin for actually enjoying the home.
Comfortable Should Mean More Than Qualifying
A lender determines whether you meet the financial requirements for a loan. That does not necessarily mean the resulting payment will feel comfortable within your lifestyle.
A home can be technically affordable while making it harder to save, travel, handle emergencies, or maintain the property properly. The strongest buying decisions leave room for both expected expenses and the surprises that eventually come with homeownership.
If you are planning to purchase a home in Little Rock or anywhere in Central Arkansas, I can help you compare more than listing prices. We can look at taxes, insurance, utilities, association costs, commuting, condition, and long-term maintenance so you understand what each option may really cost.
The right home should fit your life after closing—not just your loan approval before it.
Check out this article next